Money laundering

Publication director

🏗️ copublishing and direction of the collection: 📚Régulations & Compliance

📚Forthcoming: 🕴️L. Laref (ed.), 📕Compliance et vigilance bancaire (“Compliance and Banking Vigilance”)

► Full reference: L. Laref (ed.), Compliance et vigilance bancaire. Contribution des acteurs bancaires et financiers à la LCB-FT (Compliance and Banking Vigilance. The Contribution of Banking and Financial Actors to AML/CFT), preface by N. Vasse, “Régulations & Compliance” series, Journal of Regulation & Compliance (JoRC) and Lefebvre-Dalloz, forthcoming. - 🧮This book follows the colloquium Compliance et vigilance bancaire : la participation des acteurs du secteur bancaire et financier à la LCB/FT, at which Marie-Anne Frison-Roche spoke: 🎤“Obligation de compliance et gouvernance bancaire” (Compliance Obligation and Banking Governance). - 📝Contribution by 🕴️Marie-Anne Frison-Roche: « La contribution des banques à la lutte contre le blanchiment de capitaux et le financement du terrorisme, illustration de l’Obligation systémique de Compliance » (The Contribution of Banks to the Fight against Money Laundering and Terrorist Financing, an Illustration of the Systemic Compliance Obligation). - ► Read the presentations of the other books in the series: the following books: 🕴️M.-A. Frison-Roche, 📕Le système juridique de l’adressage de l’Internet. Une structure multi-acteurs, gage de durabilité (The Legal System of Internet Addressing. A Multi-Stakeholder Structure, the Pledge of its Sustainability), forthcoming 🕴️M.-A. Frison-Roche (ed.), 📕Le système probatoire de la Compliance, forthcoming   the previous books: 🕴️M.-A. Frison-Roche (ed.), 📕Compliance et Contrat, forthcoming 🕴️M.-A. Frison-Roche (ed.), 📕L’Obligation de Compliance, 2025 🕴️M.-A. Frison-Roche and M. Boissavy (eds.), 📕Compliance et droits de la défense. Enquête interne – CJIP – CRPC, 2024 🕴️M.-A. Frison-Roche (ed.), 📕La juridictionnalisation de la Compliance, 2023 🕴️M.-A. Frison-Roche (ed.), 📕Les Buts Monumentaux de la Compliance, 2022 🕴️M.-A. Frison-Roche (ed.), 📕Les outils de la Compliance, 2021 🕴️M.-A. Frison-Roche (ed.), 📕Pour une Europe de la Compliance, 2019 🕴️N. Borga, J.-Cl. Marin and J.-Ch. Roda (eds.), 📕Compliance : l’entreprise, le régulateur et le juge, 2018 🕴️M.-A. Frison-Roche (ed.), 📕Régulation, Supervision, Compliance, 2017 🕴️M.-A. Frison-Roche (ed.), 📕Internet, espace d’interrégulation, 2016 📚See all the books of the series. - ► Provisional table of contents: PROVISIONAL TABLE OF CONTENTS (in French) Preface by 🕴️Nicolas Vasse, Executive Director of the Anti-Money Laundering Authority (AMLA) PROPOS INTRODUCTIFS (Introductory Remarks) PERSPECTIVE GÉNÉRALE (General Perspective) ♦️ La contribution des banques à la lutte contre le blanchiment de capitaux et le financement du terrorisme, illustration de l’Obligation systémique de Compliance, by 🕴️Marie-Anne Frison-Roche PREMIÈRE PARTIE (PART ONE) LA DIFFUSION DE LA COMPLIANCE DANS LE SECTEUR BANCAIRE ET FINANCIER (THE DIFFUSION OF COMPLIANCE IN THE BANKING AND FINANCIAL SECTOR) ♦️ Quelques rappels terminologiques utiles…, by 🕴️Jérôme Lasserre Capdeville DEUXIÈME PARTIE (PART TWO) LA RÉCEPTION DE L’OBLIGATION DE COMPLIANCE PAR LES PROFESSIONNELS DU SECTEUR BANCAIRE ET FINANCIER (THE RECEPTION OF THE COMPLIANCE OBLIGATION BY BANKING AND FINANCIAL SECTOR PROFESSIONALS) ♦️ La réception de la compliance LCB-FT par le secteur bancaire et financier. Modalités d’appropriation, dysfonctionnements structurels et éthique comme condition d’effectivité, by 🕴️Jennifer Marchand ♦️ L’obligation de compliance LCB-FT, moteur de transformation des pratiques en matière de crédits et de garanties, by 🕴️Patricia Le Besnerais TROISIÈME PARTIE (PART THREE) LA MODULATION DES OBLIGATIONS DES PROFESSIONNELS DU SECTEUR BANCAIRE ET FINANCIER EN MATIÈRE DE LCB-FT (THE MODULATION OF THE AML/CFT OBLIGATIONS OF BANKING AND FINANCIAL SECTOR PROFESSIONALS) ♦️ Le banquier face au défi de la vigilance : entre exigences contradictoires et responsabilités croissantes, by 🕴️Paula Seixas et 🕴️Romain Ducatez ♦️ L’harmonisation européenne face à la modulation de l’obligation de vigilance : les enseignements de l’AMLR, by 🕴️Cassandre Degrande QUATRIÈME PARTIE (PART FOUR) COMPLIANCE ET PERFORMATIVITÉ : LES ENJEUX AUTOUR DE LA REGTECH DANS LE SECTEUR BANCAIRE ET FINANCIER APPLIQUÉE À LA LCB-FT (COMPLIANCE AND PERFORMATIVITY: THE STAKES OF REGTECH IN THE BANKING AND FINANCIAL SECTOR APPLIED TO AML/CFT) ♦️ Compliance, performativité et RegTech : la reconfiguration des dispositifs de vigilance bancaire en matière de LCB-FT, by 🕴️Gurvan Branellec ♦️ Les observations de l’ACPR sur l’usage de l’IA par les banques et néobanques — entre avancées et nouveaux défis (titre provisoire), by 🕴️Jean-Christophe Cabotte PROPOS CONCLUSIFS (Concluding Remarks) - 🌐follow Marie-Anne Frison-Roche on LinkedIn 🌐follow Marie-Anne Frison-Roche on Instagram 🌐subscribe to the Newsletter MAFR Regulation, Compliance, Law 🌐subscribe to the Video Newsletter MAFR Surplomb 🌐subscribe to the Newsletter MaFR Droit & Art

Conferences

keynote address at a conference

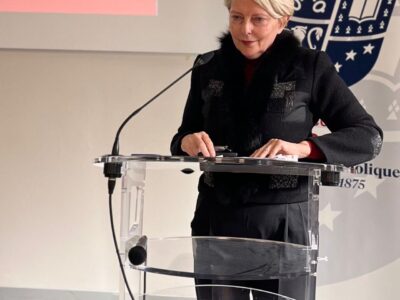
🎥Obligation de compliance et gouvernance bancaire (Compliance obligations and banking governance), in 🧮Compliance et vigilance bancaire : la participation des acteurs du secteur bancaire et financier à la LCB/FT (Compliance and Banking Vigilance: the Participation of Banking and Financial Sector Players in AML/CFT)

► Full reference : M.-A. Frison-Roche, "Obligation de compliance et gouvernance bancaire (Compliance obligations and banking governance)", in Chair in Business Ethics: Compliance, ESG and Sustainability Reporting & National Association of Bank Lawyers (ANJB), Compliance et vigilance bancaire : la participation des acteurs du secteur bancaire et financier à la LCB/FT (Compliance and Banking Vigilance: the Participation of Banking and Financial Sector Players in AML/CFT) , Faculty of Law, Catholic University of Lille, Lille, 12 March 2026. - 🧮view the full programme for the event (in French) - 📶view the slides (in French) - 🌐read the summary of this conference and the colloquium on LinkedIn - 📝This lecture will form the basis of a contribution to a forthcoming book in the 📚Régulations & Compliance series, co-published by the Journal of Regulation & Compliance (JoRC) and Lefebvre-Dalloz.   - ► English presentation of this introductory lecture of the symposium : Based on a specific method, three perspectives will be taken. In method, to shed light on the round tables making up the day's meetings without addressing the subject in their place or pretending to answer in advance the questions they will raise, or seeking to conclude in advance without having listened to anything, which is sometimes the flaw of introductions, which are so often a kind of disguised closing statement, with just a few question marks to give the impression of change, I have adopted the old, old method of the "triple funnel" introduction. This involves starting from a point other than the subject of the conference itself, Compliance and banking vigilance: the participation of banking and financial sector players in AML/CFT, in order to approach the subject from an external perspective and in a preliminary manner, nbsp;then moving on to a second external point, and doing so a third time, so that after this three-part presentation, the subject has been explored in sufficient depth to allow the following speakers to focus on the specific topic at hand. This is all the easier given that the chosen theme itself focuses on three points: a specific ambition (the "fight against money laundering and terrorist financing"), a specific sector (the "banking sector") and a specific activity carried out by individuals; three specific terms: one ambition (the "fighting agains AML/CFT""activity"). – one sectors (the "banking sector") and one active department (the "participation of stakeholders"). - My first starting point is to define what Compliance Law is in order to link Compliance Law to the subject it covers: the banking sector. Because if it were simply a matter of "being conform with applicable regulations", it is difficult to understand why the banking sector is so concerned, so constrained, so exposed to "compliance", which is simply the British way of saying "conformity". There must be more to it than simply obeying every rule and standards for preventing breaches for it, to be obliged to be so structuring and for the banking sector to be at the forefront. It therefore appears that Compliance Law is not simply mechanical obedience to a body of regulations, but rather the contribution made by systemic operators to the realisation of political ambitions that are essential for the future (the "Monumental Goals", both negative and positive). It is in this capacity that the banking sector, because it is composed of "crucial operators", is the natural subject of Compliance Law. Its power should not be criticised; it is indispensable. In an emerging branch of law that is systemic, that is Ex Ante, that is above all a Law of action whose object is the future. Techniques of conformity is only one tool. ⛏️Go further  : 🕴🏻M.-A. Frison-Roche, 📝Compliance Law, 2016 🕴🏻M.-A. Frison-Roche, 📝 Monumental goals, the beating heart of compliance law, in  🕴🏻M.-A. Frison-Roche, 📕The monumental goals of compliance, 2022 🕴🏻M.-A. Frison-Roche, 📝The Birth of a New Branch of Law: Compliance Law, 2024 🕴🏻M.-A. Frison-Roche, 📝Compliance and conformity: distinguishing between them in order to articulate them, 2024 - My second starting point is to start with the "Monumental Goals", this normative foundation of Compliance Law, and link it to this present specific case, privileged ambition of combating money laundering and terrorist financing. Certain things are surprising. Indeed, if we refuse at the introductory stage to delve into the technicalities of the texts and the litigation surrounding them, we may wonder why these two subjects (money laundering and terrorist financing) are linked in this way. We can see the correlation between banking activitird and money laundering. Notaries, auctioneers, and, in short, anyone who handles money are also involved in the fight against it. Moreover, if we see the ratio legis, the idea remains that the one who is merely the conduit (to use the familiar basis distinction in the regulatory rule of essential network infrastructure) could also be the one who organises the content: the image remains of the money laundering banker. Even if the ex ante compliance diligence whitewashes in advance, this suspicion that remains of an ex post sanction. We pay dearly for this representation, which permeates the repressive, even Criminal, Law of banking supervision, particularly in matters of secrecy, transparency, information and risk-taking. But why extend it to terrorist financing? Because the suspicion of terrorist bankers no longer exists. The case becomes clear-cut again. It is a matter of internalising within banks the sovereign responsibility to intervene before it is too late, before people are killed. Financing is the weak and visible point of systemic evil. This is understandable. It has moved from ex post (financial processing after the crime) to ex ante (financial processing before the crime). It is of a different nature. But if this is of a different nature, there is no reason to stop this Ex Ante surveillance, because money movements provide so much information about collective and individual projects. For example, in the digital space. We must be careful about this, in light of the principle of freedom, of which the principle of non-interference is only one aspect. ⛏️Go further  : 🕴🏻M.-A. Frison-Roche, 📝The Ex Ante – Ex Post Couple, Justification of a Specific Regulatory Law, in 🕴🏻M. -A. Frison-Roche, 📕Les engagements dans les systèmes de régulation, 2006 🕴🏻M.-A. Frison-Roche, 📝Ex Ante Responsability, a pillar of Compliance Law, 2022 🕴🏻M.-A. Frison-Roche, 📝Compliance, Vigilance and Civil Liability: Understanding and Keeping a Level Head, in  🕴🏻M.-A. Frison-Roche, 📕The obligation of compliance, 2025 - My third starting point is "Governance", a rather mysterious term, as it relates more to the political art of mobilising human beings than to Law. Why is it necessary for "actors" to participate, when legal norms are binding and, in most cases, take the form of Criminal Law? The combination of the most violent norms, the application of financial penalties, and even deprivation of liberty, being often claimed as a victory for financial and banking regulatory and supervisatory bodies , even as procedural principles are being rolled back, could be a source of incomprehension. Moreover, in a legal system that would be challenged by this "Governance", it is up to the State to dictate and the banks to obey. But if banks take charge of everything, it becomes difficult to maintain this system, and it is undoubtedly no longer tenable if the Monumental Goal expands to dimensions that exceed those of the State but correspond to those of the banks. The risk then is to move from one governing body to another, which is a growing social and political risk. In practical terms, banking operators can achieve this reversal in two ways. Firstly, by effectively involving the human beings who make up their organisations, both internally and externally, their partners and stakeholders. This can be called "Governance" in an alliance based on explicitcommon  goals, with contributions that are not taken at face value but are provided by "compliance structures", "credible behaviour" and "plausible trajectories". In this respect, mutual banks are in a better position than others. Training mechanisms, which are central to Compliance Law, play an essential role here. Secondly, alliances with public authorities and regional roots, with concrete assessments, are decisive. The contract then becomes not only the mandatory means by which the regulated bank fulfils its regulatory obligation, but also the most traditional legal tool by which it exercises its freedom to contribute, in its own way, to the achievement of Monumental Goals for the future of the social group, which is currently under threat. We are far beyond "conformity": this is called Compliance Law. ⛏️Find out more  : 🕴🏻M.-A. Frison-Roche, 📝A substantive Compliance Law, based on the European humanist tradition,in 🕴🏻M. -A. Frison-Roche, 📕Towards a Europe of Compliance, 2019 🕴🏻M.-A. Frison-Roche, 📝Training: content and context of Compliance Law, in 🕴🏻M. -A. Frison-Roche, 📕Compliance tools, 2020 🕴🏻M.-A. Frison-Roche, 📝Compliance Contract, compliance clauses, 2022 🕴🏻M.-A. Frison-Roche, ⚙️Compliance and Contracts, 2026 🕴🏻M.-A. Frison-Roche, 🏛️Official Mission given by the French Minister of Justice, Compliance Law, Work in progress, 2025 – 2026. - 🌐Follow Marie-Anne Frison-Roche on LinkedIn 🌐follow Marie-Anne Frison-Roche on Instagram 🌐Subscribe to the Newsletter MAFR Regulation, Compliance, Law 🌐Subscribe to the video newsletter MAFR Overhang 🌐Subscribe to the Newsletter MaFR Law & Art

Articles in The Journal of Regulation & Compliance « JoRC »

GUTMANN, Daniel🕴️

📝Droit fiscal et obligation de compliance (“Tax Law and Compliance Obligation”), in 🕴️M.-A. Frison-Roche (dir.), 📕L’obligation de Compliance (“Compliance Obligation”)

► Full Reference: D. Gutmann, "Droit fiscal et obligation de compliance" (Tax Law and Compliance Obligation), in M.-A. Frison-Roche (dir.), L'Obligation de Compliance, Journal of Regulation & Compliance (JoRC) and Dalloz, coll. "Régulations & Compliance", 2025, pp. 199-207. - ► English summary of this contribution (done by the Journal of Regulation & Compliance): The author takes up the hypothesis of a Compliance Law defined by its Monumental Goals, the realisation of which is entrusted to "crucial operators" and confronts it with Tax Law. The link is particularly effective since these operators possess what governments need in this area: relevant Information. Going further, Compliance Law can give rise to two types of obligations on the part of these operators, either towards others operators who need to be monitored, corrected or denounced, or towards themselves, when they need to make amends. In the first part of this contribution, the author shows that Compliance Obligation reproduces the mechanism of a Tax Law which, for large companies, is embroiled in a process of increasing Globalisation. It enables Governments to aspire to the "Monumental Goals" of combating tax optimisation and impoverishing governments, victims of the erosion of the tax base, in the face of the strategies of companies that are more powerful than they are themselves, by using this very power of firms to turn it against them. Companies become the willing or de facto allies of governments, particularly when it comes to recovering tax debts, or assist them in their stated ambition to achieve social justice.  In this way, the State "manages" Tax Law by cooperating with companies. In the second part, the author outlines the contours of this business Compliance Obligation, which is no longer simply a matter of paying tax. Beyond this financial obligation, it is more a question of mastering Information, particularly when multinational companies are subject to specific tax reporting obligations and are required to reveal their tax strategy, presumed to be transparent and coherent within the group : this legal presumption gives rise to obligations to seek information and ensure coherence, since a single tax strategy is not self-evident in a group. The author emphasises that companies have accepted the principles governing these new compliance obligations and are tending to transform these obligations, particularly Transparency, into a communication strategy, in line with the ESG criteria that have been developed and a desire for fruitful relations with stakeholders. Therefore the tax relations developed by major companies are being extended not only to the tax authorities, but also to NGOs, by incorporating a strong ethical dimension. This is leading to new strategies, particularly in the area of Vigilance. The author concludes: "A n’en pas douter, l’obligation de compliance existe bel et bien en matière fiscale." ("There is no doubt that the Compliance Obligation does exist in tax matters"). - 📕read the general presentation of the book, L'obligation de Compliance, in which this contribution is published -

Working papers

Working Paper for 📺Overhang

🚧Monumental Goals, normative anchoring of Compliance

► Full Reference: M.-A. Frison-Roche, Monumental Goals, normative anchoring of Compliance, Working Paper, February 2025.   - 🎬This working document has been drawn up to serve as basis to the video Overhang👁 of  the 1st February 2025: click HERE - 🎬🎬🎬In the collection of the Overhangs👁 It falls into the Notions category. ►Watch the complete collection of the Overhangs👁 : click HERE - ► Summary of this  Working Paper: Compliance, of which conformity is only one instrument (the 2 should not be confused), must be understood through the ‘Monumental Goals’ : political ambitions pursued by the public authorities and internalised in the entities in a position to achieve them, i.e. large companies. These Goals are Monumental in that they concern systems: ensuring that these systems do not collapse in the future = ‘Negative Monumental Goals’ (e.g. fight against corruption, against climate change); more ambitious still, they may aim to improve systems = ‘Positive Monumental Goals’ (e.g. effective equality between women and men). Their systemic nature gives rise to Systemic Litigation. - 🔓read the developments below⤵️ - 🌐follow Marie-Anne Frison-Roche sur LinkedIn 🌐follow Marie-Anne Frison-Roche on Instagram 🌐subscribe to the Newsletter MAFR Regulation, Compliance, Law  🌐subscribe to the Video Newsletter MAFR Overhang/Surplomb

Articles in The Journal of Regulation & Compliance « JoRC »

GUTMANN, Daniel🕴️

📝Tax Law and Compliance Obligation, in 🕴️M.-A. Frison-Roche (ed.), 📘Compliance Obligation

► Full Reference: D. Gutmann, "Tax Law and Compliance Obligation", in M.-A. Frison-Roche (ed.), Compliance Obligation, Journal of Regulation & Compliance (JoRC) and Bruylant, "Compliance & Regulation" Serie, to be published - 📘read a general presentation of the book, Compliance Obligation, in which this article is published - ► Summary of the article (done by the Journal of Regulation & Compliance – JoRC): The author takes up the hypothesis of a Compliance Law defined by its Monumental Goals, the realisation of which is entrusted to "crucial operators" and confronts it with Tax Law. The link is particularly effective since these operators possess what governments need in this area: relevant Information. Going further, Compliance Law can give rise to two types of obligations on the part of these operators, either towards others operators who need to be monitored, corrected or denounced, or towards themselves, when they need to make amends. In the first part of this contribution, the author shows that Compliance Obligation reproduces the mechanism of a Tax Law which, for large companies, is embroiled in a process of increasing Globalisation. It enables Governments to aspire to the "Monumental Goals" of combating tax optimisation and impoverishing governments, victims of the erosion of the tax base, in the face of the strategies of companies that are more powerful than they are themselves, by using this very power of firms to turn it against them. Companies become the willing or de facto allies of governments, particularly when it comes to recovering tax debts, or assist them in their stated ambition to achieve social justice.  In this way, the State "manages" Tax Law by cooperating with companies. In the second part, the author outlines the contours of this business Compliance Obligation, which is no longer simply a matter of paying tax. Beyond this financial obligation, it is more a question of mastering Information, particularly when multinational companies are subject to specific tax reporting obligations and are required to reveal their tax strategy, presumed to be transparent and coherent within the group : this legal presumption gives rise to obligations to seek information and ensure coherence, since a single tax strategy is not self-evident in a group. The author emphasises that companies have accepted the principles governing these new compliance obligations and are tending to transform these obligations, particularly Transparency, into a communication strategy, in line with the ESG criteria that have been developed and a desire for fruitful relations with stakeholders. Therefore the tax relations developed by major companies are being extended not only to the tax authorities, but also to NGOs, by incorporating a strong ethical dimension. This is leading to new strategies, particularly in the area of Vigilance. The author concludes: "A n’en pas douter, l’obligation de compliance existe bel et bien en matière fiscale." ("There is no doubt that the Compliance Obligation does exist in tax matters"). - 🦉This article is available in full text to those registered for Professor Marie-Anne Frison-Roche's courses -

Texts

Règlement (UE) 2024/1620 du 31 mai 2024 instituant l’Autorité de lutte contre le blanchiment de capitaux et le financement du terrorisme et modifiant les règlements (UE) n° 1093/2010, (UE) n° 1094/2010 et (UE) n° 1095/2010

► Full Reference: Regulation (EU) 2024/1620 of the European Parliament and of the Council of 31 May 2024 establishing the Authority for Anti-Money Laundering and Countering the Financing of Terrorism and amending Regulations (EU) No 1093/2010, (EU) No 1094/2010 and (EU) No 1095/2010 - ► read the text -

Texts

Directive (EU) 2024/1640 of 31 May 2024 on the mechanisms to be put in place by Member States for the prevention of the use of the financial system for the purposes of money laundering or terrorist financing

► Référence complète : Directive (EU) 2024/1640 of the European Parliament and of the Council of 31 May 2024 on the mechanisms to be put in place by Member States for the prevention of the use of the financial system for the purposes of money laundering or terrorist financing, amending Directive(EU) 2019/1937, and amending and repealing Directive (EU) 2015/849 - ► read the text -

Lessons

Teaching for the École nationale de la magistrature - ENM (French National School for the Judiciary)

⚖️Droit de la compliance (Compliance Law)

► Full Reference: F. Ancel &  M.-A. Frison-Roche, Droit de la compliance (Compliance Law), École nationale de la magistrature – ENM (French National School for the Judiciary), in collaboration with the École de Formation professionnelle des Barreaux du ressort de la cour d'appel de Paris – EFB (Paris Bar School), Paris, February 1 and 2, 2024 This teaching is given in French. - 🌐consult on LinkedIn a general présentation of this event, which links to a presentation and a report of each speech - ► Presentation of the Teaching: The aim of this two-day conference is to enable judges and lawyers to grasp the issues, objectives and methods that define Compliance Law as it is practised in companies. The speakers will illustrate the growing trend towards litigation, which is difficult to reconcile with the supranational dimension, or even indifference to territories, for example when disputes concern systemic climate or digital issues: the result is a renewal of the role of the judge and the role of lawyers. This must be set against the renewal of the role and operation of companies themselves. This is analysed from the perspective of Civil Law, in particular Contract Law and Liability Law. Company Law and Criminal Law are also addressed, as well as the way in which the legal system now integrates governance, regulation, climate and digital issues and the smooth operation of financial markets through Compliance techniques. - ► Organisation of the Teaching: This conference is divided into two parts. The first day is designed as a presentation of the major themes through which Compliance Law crosses the branches of traditional Law. The speakers will be professors of Law who will successively summarise the branches of Law and put into perspective the way in which Compliance imperatives give rise to new situations, new difficulties and new solutions. This enables the second day to focus on practical and topical issues and to debate controversial questions between people of different sensibilities. The participants tend to be judges, members of regulatory authorities, lawyers, members of associations and so on. - ► Enrolment procedure: The course is open to all judicial and consular magistrates, as well as lawyers. Registrations can be made directly with the ENM or with the EFB. - ► Speakers :   🎤François Ancel, Judge at the Première Chambre civile de la Cour de cassation (First Civil Chamber of the French Court of cassation)  🎤Thomas Baudesson, Attorney at the Paris Bar, Partner at Clifford Chance 🎤Guillaume Beaussonie, Full Professor at Toulouse 1 Capitole University 🎤Jacques Boulard, Premier Président de la Cour d’appel de Paris (First President of the Paris Court of Appeal) 🎤Marie Caffin-Moi, Full Professor at Paris Panthéon-Assas University 🎤Malik Chapuis, Judge at the Tribunal judiciaire de Paris (Paris First Instance Civil Court) 🎤Lucie Chatelain, Advocacy and Litigation Manager – Civil Liability of Parent Companies, Sherpa 🎤Jean-Benoît Devauges, Directeur Juridique, Ethique et Gouvernance des entreprises (Legal, Ethics and enterprises governance Director), MEDEF 🎤Marie-Anne Frison-Roche, Professor of Regulatory and Compliance Law, Director of the Journal of Regulation & Compliance (JoRC) 🎤Arnaud Gossement, Attorney at the Paris Bar, Partner at Gossement Avocats 🎤Thibault Goujon-Bethan, Full Professor at Jean Moulin Lyon 3 University 🎤Christophe Ingrain, Attorney at the Paris Bar, Partner at Darrois Villey Maillot Brochier 🎤Isabelle Jegouzo, Director of the Agence française anticorruption – AFA (French Anti-Corruption Agency)  🎤Anne-Valérie Le Fur, Full Professor at Versailles Saint-Quentin-en-Yvelines University 🎤Charlotte Michon, Attorney at the Paris Bar, partner at Charlotte Michon Avocat 🎤Jean-Baptiste Racine, Full Professor at Paris Panthéon-Assas University 🎤 Jean-Christophe Roda, Full Professor at Jean-Moulin Lyon 3 University 🎤Jérôme Simon, 1er Vice-Procureur Financier (First Financial Vice-Prosecutor) - 🧮read below the programme put together and organised by François Ancel and Marie-Anne Frison-Roche, as well as the reports of each presentation⤵️ - 🌐follow Marie-Anne Frison-Roche on LinkedIn 🌐follow Marie-Anne Frison-Roche on Instagram 🌐subscribe to the Newsletter MAFR Regulation, Compliance, Law

Breaking news

📧 On June 3, 2021, UK Financial Markets Authority skillfully expresses its position on the interference of cryptocurrencies on criminal interference and consumer protection

►  Money Laundering, Cryptocurrency and the Art of Saying It: the Financial Conduct Authority (FCA) statement of June 3, 2021 and the Art of Saying It. Law is softer than ever.   The English have their way of saying things: thus the Financial Conduct Authority -FCA, the British financial market regulator, published on June 3, 2021 a press release whose expression is remarkable. Its subject matter is crypto-assets and, like in an essay plan à la française, it is built in two parts.  In the part I, it is just mentioned that the deadline for companies in this industry to obtain a registration, which was due to end soon, will be postponed to March 2022. Why? Because almost all of them have not been able to demonstrate their ability not to be resistant to money laundering and other criminal activities. This is in no way presented as a conviction, just the objective cause of a postponement of the date, the time for the Financial Regulatory Authority to better examine the files, themselves to be completed by applicants. The part II concerns consumer protection. The Authority point out that the consumer can lose everything in an extremely risky products and underlines that it is unlikely that this ruined layman will even be able to access the ombudsman to obtain anything. It is purely informative. This is how the English bodies formulate their opinion on cryptoasset. It's elegant (the press is more direct). This also makes it possible not to be covered with insults by the worshipers of these objects: are expressed just a technical delay granted and not a conviction that cryptoasset could be per se  an instrument of criminality, just a probationary difficulty ; and just a regret on the non-access to the ombudsman for these cryptoassets consumers. But if the evolution of the bubble leads these investors to ruine shows, the Regulator will have warned and expressed in advance the regrets he had of the lack of legal technique to protect them. And if the facts show that it is massively through cryptocurrency that the crime is whitewashed, the Regulator has shown everyone his prudence, the delay it will have take to examine the files  and its kind foresight. No one more than a British knows what Liability is.    -        

Jurisprudence

Autorité de Contrôle Prudentiel et de Résolution (French Banking Regulator), Commission des sanctions (Commission of sanctions)

Decision of 24th of February 2021 2021, ING France

Full reference: Autorité de Contrôle Prudentiel et de Résolution (French Banking Regulator), Commission des sanctions (Commission of sanctions), 24th of February 2021, ING Bank France, procedure n°2020-02   Read the decision (in French)   In this decision, the ACPR Sanctions Commission condemns IGN Bank France to a reprimand and a financial penalty of 3 million euros because of the inadequacy of its measures to fight corruption, money laundering and financing of terrorism.   Extract from the decision summarizing ING France's breaches of its Compliance obligations to fight against corruption, money laundering and financing of terrorism: "At the time of the on-site check, ING France's risk classification was incomplete and ineffective (grievance 1) and its system for monitoring its business relations (complaint 2) and their operations (grievance 4) presented serious deficiencies, as well as its organization and procedures for fund transfers (grievance 3). The updating of customer knowledge was insufficient (grievance 5), as were the detection of PEPs and the implementation of measures due diligence for this category of clientele (grievance 6). For the implementation of its due diligence obligations, numerous shortcomings were noted, whether these were breaches of the obligation to carry out a reinforced examination (grievance 7) or breaches of the obligation to send Tracfin a DS, initial (grievance 8) or additional (grievance 9). Finally, the detection of persons subject to an asset freezing measure was not fully effective (grievance 10) " (our translation of the decision which is only available in French).

Articles

💬Et si le secret de l’avocat était l’allié de la lutte contre le blanchiment ? (Why would the attorney not be an ally in the fight against money laundering?)

Full reference: Frison-Roche, M.-A., Et si le secret de l’avocat était l’allié de la lutte contre le blanchiment ?, interview realized by Olivia Dufour for Actu-juridiques, Lextenso, 15th of October 2020 Read the interview (in French) To go deeper on the place of the attorney in Compliance Law, read Marie-Anne Frison-Roche's working paper: The Attorney, Vector of Conviction in the New Compliance System

Articles

Attorney’s Professional Secret & Filter mechanism in balance with fighting Money Laundering: constitutional analysis in favor of Attorney’s Secret

Full Reference : Frison-Roche, M.-A.,Attorney's Professional Secret & Filter mechanism in balance with fighting Money Laundering: constitutional analysis in favor of Attorney's Secret, Newsletter MAFR – Law, Compliance, Regulation, October 9, 2020.   Summary: By its judgment of September 24, 2020, the Constitutional Court of Belgium released an essential judgment which considers: – Compliance Law which imposes obligations on entities to fight against money laundering and the financing of terrorism is legal requirements which must be analyzed on the basis of these goals – the national transposition law is "broader" than the transposed European texts since it is anchored in the Constitution – the provisions of the law imposing the declaration of suspicion on an employee of the Attorney or on a Compliance Officer concerning information covered by the professional secrecy of the Attorney, the basis of Democracy, must therefore be canceled. This reasoning is remarkable and very solid. It is not unique to Belgium.   Lire par abonnement gratuit les autres News dans la Newsletter MAFR – Law, Compliance, Regulation

Jurisprudence

Constitutional Court of Belgium

Decision of the Constitutional Court of Belgium of 24th of September 2020 concerning the partial annulment appeal of the law of 18th of September 2017

Full reference: Constitutional Court of Belgium, 24th of September 2020, Décision concernant le recours en annulation partielle de la loi du 18 septembre 2017 relative à la prévention du blanchiment de capitaux et du financement du terrorisme et à la limitation de l'utilisation des espèces (decision concerning the partial annulment appeal of the law of 18th of September 2017 related to money laundering and terrorism financing prevention and to the restriction of the use of cash), n°114/2020 Read the decision (in French) Read the law of 18th of September 2017 (in French)

Articles

Interregulation: way of “cooperation protocol”​ between Regulatory Bodies.Example between French Financial Markets Authority and Anticorruption Agency

Full reference: Frison-Roche, M.-A., Interregulation: way of "cooperation protocol"​ between Regulatory Bodies. Example between French Financial Markets Authority and Anticorruption Agency, Newsletter MAFR – Law, Compliance, Regulation, 22nd of September 2020 Read by freely subscribing other news of the Newsletter MAFR – Law, Compliance, Regulation   Summary of the news:  Although Regulation Law was born from the notion "sector", constant interferences between sectors and frequent interactions between some sectors and more general questions common to different sectors, make interregulation necessary. Compliance Law being the extension of Regulation Law, this interregulation mechanism is also necessary in Compliance Law.  This interregulation can take many legal paths like letters exchanges between regulators, the creation of a network of regulators and supervisors at the world level or about some specific question or the adoption of a "cooperation protocol" as the AMF (French Financial Market Regulator) and the AFA (French Anticorruption Agency) did on 16th of September 2020 to reinforce their respective fight against corruption, against market abuses and for the protection of investors.  This cooperation protocol between the AFA and the AMF has the following subjects: A more efficient methodology concerning the research and the analysis of corruption and market abuses. A more efficient prevention of corruption and market abuses. A better capacity to give recommendations of new regulations to the Legislator. A more rigorous monitoring of international works on the topic.  A more coherent information for the public. Are regulators the new teachers? 

Articles

Compliance & Regulatory Soft Law, legal Certainty and Cooperation: example of the U.S. Financial Crimes Enforcement Network new Guidelines on AML/FT.

Full reference: Frison-Roche, M.-A., Compliance & Regulatory Soft Law, legal Certainty and Cooperation: example of the U.S. Financial Crimes Enforcement Network new Guidelines on AML/FT, Newsletter MAFR – Law, Compliance, Regulation, 2nd of September 2020 Read by freely subscribing other news of the Newsletter MAFR – Law, Compliance, Regulation   Summary of the news The Financial Crimes Enforcement Network (FinCEN) is an organ, depending on the American Treasury, in charge of fighting against financial criminality and especially against money laundering and terrorism financing. For this, it has large control and sanction powers.  In August 2020, the FinCEN published a document untitled "Statement on Enforcement" which aimed to explicit its control and sanction methods. It reveals what firms risk in case of offense (from the simple warning letter to criminal pursuits passing through financial fines) and the different criteria on which FinCEN is based to use one sanction rather than another. Among these criteria, we find for examples the nature and the seriousness of committed violations or the firm's history but also the implementation of compliance program or the quality and the spread of the cooperation with FinCEN durning the investigation.  One of the objectives of the publication of such an information document is to obtain the cooperation of firms by creating a confidence relationship between the regulator and the regulated firm. However, it is very difficult to ask to the firms to cooperate and to furnish information if they can fear that this same information can be used later as proof against them by the FinCEN.  Another objective is to reinforce legal security and transparency. However, the FinCEN's declaration does not seem to commit it, because it is not presented as a chart but as a simple declaration. Indeed, the list of the possible sanctions and the criteria used by the FinCEN are far from being exhaustive and can be completed in concreto by the FinCEN without any justification.

Articles

Against money laundering, what time matters? Does it work, between ExAnte and ExPost? (BIL case)

Full reference: Frison-Roche, M.-A., Against money laundering, what time matters? Does it work, between ExAnte and ExPost? (BIL case), Newsletter MAFR – Law, Compliance, Regulation, 11th of August 2020 Read, by freely subscribing, the other news in the Newsletter MAFR – Law, Compliance, Regulation   Summary of the news The activity of money laundering is detrimental not only in itself but also because it permits the development and the sustainability of other criminal activities such as drug trafficking, weapon trafficking or human beings selling. Fighting against money laundering could permit to indirectly fight against these underlying activities, by the way very difficult to fight. Thus, the fight against money laundering has become a "monumental goal", which justifies the adoption of tools sometimes much more powerful than those used by classical criminal Law. For the sake of efficiency, the legal obligation to prevent money laundering is given to every body able to do it, as banks, real estate agents or gaming society, under the penalty of sanction.  On 10th of August 2020, the Luxembourgish financial market supervisor convicts the International Bank of Luxembourg to pay a fine of 4,5 millions of euros because of weaknesses detected in its process of fight against money laundering. However, when the sanction has been pronounced, the bank had already remedied the weaknesses identified. It is important to observe that what is important for Compliance Law, it is not that a non compliant behavior is punished but rather that the crucial firm modifies its behavior in order to being more efficient in the realization of the "monumental goal", only concern of the public authority. Thus, an Ex Post sanction against the crucial operator is not an end in itself and can be justified only if it permits to incite the crucial operator to act or rather to desincite to do anything. Compliance Law is an Ex Ante legal system.    To go further, read:  Frison-Roche, M.-A., Le couple Ex Ante – Ex Post, justificatif d'un droit spécifique et propre de la Régulation, 2006 (in French)

Videos

The French Council of State (Conseil d’État) confirms the wide and therefore severe application of the sanctions mechanism in the Compliance Law concerning the freezing of assets, by its decision of November 15, 2019, La Banque Postale v. ACPR

Watch the video explaining the content, meaning and scope of the decision made by the Conseil d'État (French Council of State) on November 15, 2019, La Banque Postale v. Autorité de contrôle prudentiel et de résolution (ACPR). The Autorité de contrôle prudentiel et de résolution – ACPR (French Authority of prudential control and resolution) pronounced a very high sanction, representing 7% of La Banque Postale's net annual result. The breach is constituted by the fact of not having prevented the use of the banking technique of the "money order" which was used to escape the freezing of the assets. The Conseil d'État recalls that by nature if the assets are frozen, it is not possible that anyone is able to dispose of these assets. However, by the use of "money orders", persons targeted by asset freezing decisions, tools used in connection with the fight against money laundering and the fight against terrorism, had been able to circulate money to from accounts managed by La Banque Postale, of which they were not customers. This case was not foreseen at the time when the Bank Postale was sanctioned by the ACPR for not having prevented such a use, the texts forcing it under its obligations of "conformity" to prevent this behavior of violation background gels on the part of his customers, but only that. This case of a use of a means by a person who is not a customer of the bank was not foreseen at the time when the alleged facts took place and the Bank claims not to be able to be punished since in the repressive matter it is necessary to respect the principle of non-retroactivity of the texts, – in this case texts later supplemented to aim at such an assumption -, the non-retroactivity being a major principle itself related to the principle of the legality of the offenses and the penalties. We are therefore in the hypothesis of a silence of the texts. What to decide? Can the Bank be condemned and so heavily or not by the ACPR? The Bank does not think so.  It acted against this sanction decision firstly because those who used these money orders were not its clients. It has strong reasons to avail itself of this fact, since subsequently the texts needed to be modified to aim not only the use of this technique of money order by those who have a count in the bank and also by those who act with cash through the bank without a count, that is to say without an account holder to look at. Because we are in criminal matters, the restrictive interpretation and non-retroactivity of the text should lead to follow the reasoning of the Bank. But the Conseil d'État does not because it considers that implicitly but necessarily even with this subsequent modification of the text, it had aimed that use before. By this way, the Conseil d'Étatuncil develops a very broad concept of the obligations of banks in their role in the fight against money laundering, and therefore a very repressive point of view, which permeates their "obligation of Compliance". Thus, when the bank also argues that it can not be sanctioned since for it this activity of money order is  deficit and that it did not cause harm to its customers even by assuming badly its obligations, theConseil d'État stresses that this is not a pertinent perspective since the Compliance obligations falls within the "overriding general interest of protection of public order and public security, to which the freezing of assets legislation responds". -   Read the  judgment of the Conseil d'État ( in French). 

Articles in The Journal of Regulation & Compliance « JoRC »

On June 21, 2019, for the sole purpose of combating money laundering and terrorist financing, the FATF publishes a comprehensive system of supervision of ” =crypto-products” platforms

In what it presents as a set of guidelines designed by a risk-driven approach, the FATF published on 21 June 2019 recommendating to fight the use of crypto-assets and cryptocurrency platforms for launderind money and financing terrorism. This fight against money laundering is (with the fight against corruption) often presented as the core of the Compliance Law. The FATF takes a large part of it. Even if this new branch of Law aims to crystallize other ambitions, such as the fight against tax fraud or climate change, or even the promotion of diversity or education and the preservation of democratie, the legislation of Compliance Law are mature in the matter of money laundering and the terrorism financing, as they are in the fight against corruption. The news comes then not from the new legal mechanisms but rather from the new technological tools that could allow the realization of the behaviors against which these obligations of compliance have been inserted in the legal system. It is then to these technologies that the law must adapt. This is the case with crypto-assets and cryptocurrency platforms. Because these are rapidly evolving technologies, with the exercise of written guidelines in 2019 to inform the meaning of the provisions adopted in 2018, the FATF is taking the opportunity to change the definition it provides of crypto-assets and cryptocurrencies. So that a too narrow definition by the texts does not allow the operators to escape the supervision (phenomenon of "hole in the racket" – loophole)..     -   In fact, in October 2018, the FATC (Financial Action Task Force) developed 15 principles applying to these platforms, to allow this intergovernmental organization to carry out its general mission to combat money laundering and the financing of terrorism. These June 2019 recommendations are to interpret them.   In this very important document, where it is expressly stated that it is a matter of fixing the obligations of those who propose crypto-assets and crypto-currencies, the notion of self-regulation is rejected. Il est writter : "Regarding VASP (virtual assets services providers) supervision, the Guidance makes clear that only competent authorities can act as VASP supervisory or monitoring bodies1souligné par nous, and not self-regulatory bodies. They should conduct risk-based supervision or monitoring, with adequate powers, including the power to conduct inspections, compel the production of information and impose sanctions. There is a specific focus on the importance of international co-operation between supervisors, given the cross-border nature of VASPs’ activities and provision of services." On the contrary, it is a matter of elaborating the control obligations that these service providers must exercise over products and their customers (Due Diligences), which must be supervised by public authorities.  In order to exercise this supervision and monitoring, the national authorities themselves must ensure that they work together : "As the Virtual Assets Services Providers (VASP) sector evolves, countries should consider examining the relationship between AML/CF (Anti-Money Laundering and Counter Terrorist Financint) measures for covered VA activities and other regulatory and supervisory measures (e.g., consumer protection, prudential safety and soundness, network IT security, tax, etc.), as the measures taken in other fields may affect the ML/TF risks. In this regard, countries should consider undertaking short- and longer-term policy work to develop comprehensive regulatory and supervisory frameworks for covered VA activities and VASPs (as well as other obliged entities operating in the VA space) as widespread adoption of VAs continues". After particularly interesting comparative law information on Italy, the Scandinavian countries and the United States, the report concludes: "International Co-operation is Key", because of the global nature of this activity.   Since the issue is not the global Regulation of these platforms and types of products, but only the possible modes of money laundering and terrorist financing to which they may give rise, the FATF recalls that neither crypto-products nor product suppliers are not referred to as such. As the guidance's title recalls, common to the 2018 document adopting the 15 principles and this interpretive document, these are "risk-based" rules. Thus, it is according to the situations that these – products and suppliers – that they may or may not present risks of laundering and financing of terrorism: depending on the type of transaction, the type of client, the type of country, etc. For example, from the moment that the transaction is anonymous, that is impossible to know the "beneficiary", or that it is transnational and instantaneous, which makes it difficult to supervise because of the heterogeneity of national supervisions little articulated between them. In reports that public supervisors must have with crypto-product suppliers, they must adjust according to the level of risk presented by them, higher or lower: "Adjusting the type of AML/CFT supervision or monitoring: supervisors should employ both offsite and onsite access to all relevant risk and compliance information.However, to the extent permitted by their regime, supervisors can determine the correct mix of offsite and onsite supervision or monitoring of Virtual Assets Services Providers (VASPs). Offsite supervision alone may not be appropriate in higher risk situations. However, where supervisory findings in previous examinations (either offsite or onsite) suggest a low risk for ML/TF, resources can be allocated to focus on higher risk VASPs. In that case, lower risk VASPs could be supervised offsite, for example through transaction analysis and questionnaires". This "adjustment" required does not prevent a very broad conception of the power of supervision. So, for nothing escapes the recommendations (and in particular the obligations that ensue for the suppliers of these products), the definition of the crypo-assets and crypo-currencies is this one: “Virtual asset” as a digital representation of value that can be digitally traded or transferred and can be used for payment or investment purposes. Virtual assets do not include digital representations of fiat currencies, securities, and other financial assets that are already covered elsewhere in the FATF Recommendations." And for the same reason of effectiveness is posited the principle of technological neutrality: "Whether a natural or legal person engaged in Virtual Assets (VA) activities is a Virtual Asset Services Provider (VASP) depends on how the person uses the VA and for whose benefit. As emphasized above, …  then they are a VASP, regardless of what technology they use to conduct the covered VA activities. Moreover, they are a VASP, whether they use a decentralized or centralized platform, smart contract, or some other mechanism.". The interpretative guidelines then formulate the obligations that these platforms have with regard to the supervisors they obey(question of the "jurisdiction", ratione loci ; ratione materiae): " The Guidance explains how these obligations should be fulfilled in a VA context and provides clarifications regarding the specific requirements applicable regarding the USD/EUR 1 000 threshold for virtual assets occasional transactions, above which VASPs must conduct customer due diligence (Recommendation 10); and the obligation to obtain, hold, and transmit required originator and beneficiary information, immediately and securely, when conducting VA transfers (Recommendation 16). As the guidance makes clear, relevant authorities should co-ordinate to ensure this can be done in a way that is compatible with national data protection and privacy rules. ". These platforms are not uniformly defined due to the diversity of their activities. Because it is their activity that makes them responsible for this or that regulator. For example from the Central Bank or the Financial Regulator: "For example, a number of online platforms that provide a mechanism for trading assets, including VAs offered and sold in ICOs, may meet the definition of an exchange and/or a security-related entity dealing in VAs that are “securities” under various jurisdictions’ national legal frameworks. Other jurisdictions may have a different approach which may include payment tokens. The relevant competent authorities in jurisdictions should therefore strive to apply a functional approach that takes into account the relevant facts and circumstances of the platform, assets, and activity involved, among other factors, in determining whether the entity meets the definition of an “exchange”2Underlined by us. or other obliged entity (such as a securities-related entity) under their national legal framework and whether an entity falls within a particular definition. In reaching a determination, countries and competent authorities should consider the activities and functions that the entity in question performs, regardless of the technology associated with the activity or used by the entity".   - Reading this very important document, it is possible to make 6 observations:  1. Interpretative documents are often more important than rules interpretated themselves. En these guidances, first and foremost, these are major obligations that are stated, not only for platforms but also for national laws, and well beyond the issue of money laundering. So, it is laid: "Countries should designate one or more authorities that have responsibility for licensing and/or registering VASPs. …  at a minimum, VASPs should be required to be licensed or registered in the jurisdiction(s) where they are created. ".This is a general prescription, involving a general regulation of these platform, which registered in a general way, will probably be supervised in a general way. Secondly, it is a series of binding measures that is required of the National legal systems, for example the possibility of seizing crypto-values. It shows that the soft Law illustrates the continuum of the texts, and allows their evolution. Here the evolution of the definition of the object itself: the definition of crypto-assets and crypto-currencies is widened, so that the techniques of money laundering and terrorist financing are always countered, without it being necessary to adopt new binding rules. We are beyond mere interpretation. And even more of the principle of restrictive interpretation, classically attached to the Repressive Law … 2. Fort the effectiveness of the Compliance Law, definition become extremely broad. Thus, to follow the FATF, the definititon off a financial institution is as follows: "“Financial institution” as any natural or legal person who conducts as a business one or more of several specified activities or operations for or on behalf of a customer". This is more the definition of a company in Competition Law3Plus loin, le texte donne une définition plus détaillée : "When determining whether a specific activity or entity falls within the scope of the definition and is therefore subject to regulation, countries should consider the wide range of various VA services or business models that exist in the VA ecosystem and, in particular, consider their functionality or the financial activities that they facilitate in the context of the covered VA activities (i.e., items (i) through (v) described in the VASP definition above). Further, countries should consider whether the activities involve a natural or legal person that conducts as a business the five functional activities described for or on behalf of another natural or legal person, both of which are essential elements to the definition and the latter of which implies a certain level of “custody” or “control” of the virtual asset, or “ability to actively facilitate the financial activity” on the part of the natural or legal person that conducts the business for a customer."….Why ? Because otherwise, an operator finds a status allowing him to escape the category and obligations listed. The principle of efficiency implies it. The principle of "legality", derived from criminal law, has hardly any existence. But this also corresponds to the general evolution of the financial world, in which one no longer stars from the organ (for example to be a"bank") but of activity, but from an activity or a fonction whose metamorphoses are so rapid that it is almost impossible to define them …. 3. In the same way, the definition of crypto-assets or crypto-currencies: "“Virtual asset” as a digital representation of value that can be digitally traded or transferred and can be used for payment or investment purposes. Virtual assets do not include digital representations of fiat currencies, securities, and other financial assets that are already covered elsewhere in the FATF Recommendations". This definition is purely operational because nothing can escape the FATF: all that is financial or monetary, whatever its form or support, its traditional form or a form that will be invented tomorrow, is within its competence and, through a such definition, is under national supervisors. In Compliance Law, and since everything is based on risk analysis, the idea is simple: nothing must escape obligations and supervision. 4. Platform apprehension is done by the criterion of activity, according to the "functional" method. Thus, its supervision, or even its regulation, and its obligations of compliance, will apply, depending on what it does, to the Financial Regulator (if it does ICO) or to others if it only uses tokens as an instrument of exchange. If it makes several uses, then it would fall under several Regulators (criterion ratione materiae). 5. The principle of "technological neutrality" is a classic principle in Telecommunications Law. Here we measure the interference between the principles of Telecommunications Law and Financial Law, which is logical because crypto-financial objects are born of digital technology. This neutrality allows both technological innovation to develop and supervision to be unhindered for not having foreseen an innovative technology appearing after the adoption of the legal text. Here again, the effectiveness of Compliance and risk management are served, without the innovation being thwarted, which is often opposed. 6. What is expected of national public authorities is a very wide "interregulation". This is both "positive". Indeed, this includes financial matters but also the security of networks, or the protection of consumers. It can be called equilibrium interregulation in that all goals converge. But this is also an "interregulation" that can be described as balance. Indeed, the FATF is concerned about the protection of personal data. However, it emphasizes that the effectiveness of the Compliance system must stop. But the protection of personal data is also a part of Compliance Law…. This is one of the major challenges in the future: the balance between security and the fight against global evils(here the fight against money laundering and terrorism) and the protection of the privacy of individuals, as both fall under Compliance, but both have opposite legal effects: one the transmission of information, and the other the secret of the information.  -