Payment

Articles in The Journal of Regulation & Compliance « JoRC »

📝Les technologies de conformité pour satisfaire les exigences du droit de la compliance. Exemple du numérique (Conformity technologies to meet Compliance Law requirements. The digital example), in 🕴️M.-A. Frison-Roche (dir.), 📕L’obligation de Compliance

► Full Reference : E. Netter, "Les technologies de conformité pour satisfaire les exigences du droit de la compliance. Exemple du numérique" (Conformity technologies to meet the requirements of Compliance Caw. Digital example), in M.-A. Frison-Roche (dir.), L'obligation de Compliance, Journal of Regulation & Compliance (JoRC) and Dalloz, coll. "Régulations & Compliance", 2025, pp. 355-367. - 📕read the general presentation of the book, L'obligation de Compliance, in which this contribution is published. - ► English summary of this contribution (done by the Journal of Regulation & Compliance) :The author distinguishes between Compliance, which refers to Monumental Goals, and conformity, which are the concrete means that the company uses to tend towards them, through processes, check-lists in the monitoring of which the operator is accountable (art. 5.2. GRPD). Technology enables the operator to meet this requirement, as the changing nature of technology fits in well with the very general nature of the goals pursued, which leave plenty of room for businesses and public authorities to produce soft law. The contribution focuses firstly on existing technologies. Through Compliance, Law can prohibit a technology or restrict its use because it runs counter to the goal pursued, for example the technology of fully automated decisions producing legal effects on individuals. Because it is a perilous exercise to dictate by law what is good and what is bad in this area, the method is rather one of explicability, i.e. control through knowledge by others. Regulators are nevertheless developing numerous requirements stemming from the Monumental Goals of Compliance. Operators must update their technology or abandon obsolete technology in the light of new risks or to enable effective competition that does not lock users into a closed system. But technological power must not become too intrusive, as the privacy and freedom of the individuals concerned must be respected, which leads to the principles of necessity and proportionality. The author stresses that operators must comply with the regulations by using certain technologies if these technologies are available, or even to counteract them if they are contrary to the goals of the regulations, but this obligation of conformity is applied only if these technologies are available. The notion of "available technology" therefore becomes the criterion of the obligation, which means that its content varies with circumstances and time, particularly in the area of cybersecurity. In the second part of this contribution, the author examines technologies that are only potential, those that Law, and in particular the courts, might require companies to invent in order to fulfill their conformity obligation. This is quite understandable when we are talking about technologies that are in the making, but which will come to fruition, for example in the area of personal data transfer to satisfy the right to portability (GRPD), or where companies must be encouraged to develop technologies that are of less immediate benefit to them, or in the area of secure payment to ensure strong authentication (SPD 2). This is more difficult for technologies whose feasibility is not even certain, such as online age verification or the interoperability of secure messaging systems, two requirements which appear to be technologically contradictory in their terms, and which therefore still come under the heading of "imaginary technology". But Compliance is putting so much pressure on companies, particularly digital technology companies, that considerable investment is required to achieve it. The author concludes that this is the very ambition of Compliance and that the future will show how successful it will be.          - 🦉This article is available in full texte for persons following Professor Marie-Anne Frison-Roche teaching. -
Working papers

Working Paper for 📺Overhang (News)

🚧The Contract, a Compliance tool: the Obligation for a platform to control content (French Supreme Judicial Court, 15 January 2025) :

► Full Reference: M.-A. Frison-Roche, The Contract, a Compliance tool: the Obligation for a platform to control content CE, 27 January 2025, B. c/ CNIL, Working Paper, March 2025. - 🎤 This Working Paper was developed as a basis for the Overhang👁 video  on 29 March 2025 : click HERE (in French) - 🎬🎬🎬In the collection of the Overhangs👁 It falls into the News category. ►Watch the complete collection of the Overhangs👁 : click HERE - ► Summary of this Working Paper: The ruling handed down on 15 January 2025 by the Commercial, Economic and Financial Chamber of the French Judicial Supreme Court (Cour de cassation) provides a solution to the issue of content control in the digital environment. It resolves what appears to be the aporia so often emphasised, and even claimed, namely the impossibility of developing an effective controlling technology. To do this, the Court disregarded the applicable laws and referred to the electronic payment contract between the bank and the platform, which contained a clause on Vigilance against unlawful content, linked to a termination clause. It held that this clause was fully effective. This solution, so simple and so strong, can make a major contribution to regulating the digital space, if the banks so wish, because what platform can do without reliable electronic payment services?   - 🔓read the developments below⤵️ - 🌐follow Marie-Anne Frison-Roche sur LinkedIn 🌐follow Marie-Anne Frison-Roche on Instagram 🌐subscribe to the Newsletter MAFR Regulation, Compliance, Law  🌐subscribe to the Video Newsletter MAFR Surplomb

Publication director

🏗️ direction of the collection: 📚Cours Dalloz – Série Droit privé

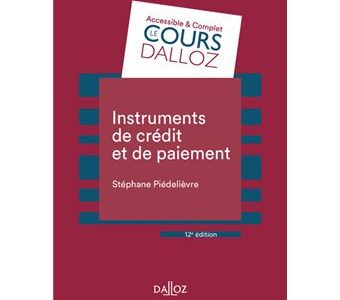
📚Publication of : 🕴️Stéphane PIÉDELIÈVRE, 📕Instruments de crédit et de paiement (Credit and Payment Instruments), 12th ed.

► Full Reference : S. Piédelièvre, Instruments de crédit et de paiement (Credit and Payment Instruments), 12th ed., 2022, Dalloz, “Cours Dalloz-Série Droit privé” Series, 453 p. - ► General presentation of the book (written in French) : The book first sets out the theory of accounts. Then the credit instruments, namely commercial paper and the new credit instruments. In the second part of the book, payment instruments are explained, namely the cheque and the new means of payment. This textbook thus makes it possible to understand the legal instruments through which companies obtain credit and pay the claims that third parties hold against them: the bill of exchange, the promissory note or the cheque, the whole most often operating through a bank account. In this tradition, which remains rooted in civil law whose guiding principles continue to govern the subject, the modernity of certain instruments renews it, such as the Dailly assignment or electronic money, which is upsetting the law of payment. This clear and above all pedagogical textbook explains this dialectic between classic law and the modernity of techniques. - 📚See the entire collection in which the book is published. -

Articles

“Interregulation”​ between Payments System and Personal Data Protection: how to organize this “interplay”​?

Full reference: Frison-Roche, M.-A., "Interregulation"​ between Payments System and Personal Data Protection: how to organize this "interplay"​?, Newsletter MAFR – Law, Compliance, Regulation, 27th of August 2020 Read by freely subscribing the other news of the Newsletter MAFR – Law, Compliance, Regulation   Summary of the news Regulation Law, in order to recognize and draw the consequences from the specificities of some objects, has been build, at the start, around the notion of "technical sector" although their delimitation is partially related to a political choice. But, in facts, there are multiple points of contacts between sectors, actors moving from one to another as objects. The regulatory solution is so to climb over some technical borders through the methodology of interregulation which is by the way the only one to enable the regulation of some phenomena going beyond the notion of sector and related to Compliance Law.  This news takes the exemple of companies furnishing new payment services. In order to they can provide these services, these firms needs to access to banking accounts of concerned people and so to very sensitive personal data. Regulation of such a configuration needs a cooperation between the banking regulator and the personal data regulator. Legislation being not sufficient to organize in Ex Ante this interregulation, the European Data Protection Board has published some guidelines on 17th of July 2020 about the way it conceives the articulation between the PSD2 (European directive about payment services) and GDPR and has announced that it intended to expand the circle of its interlocutors to do this interregulation. Such an initiative from EDPB can be justified by the uncertainty  about how interpreting both texts and articulating them.   

Articles in The Journal of Regulation & Compliance « JoRC »

On June 18, 2019, during its meetings with the banking sector, the Single Resolution Board tells what it expects for it (and its Regulators) for the effectiveness of the Resolution mechanism.

The European Banking Union is based on supervision as much as on regulation: it concerns the operators as much as the structures of the sector, because the operators "hold" the sector. This is why the "regulator – supervisor" holds the operators by the supervision and is close to them. He meets them officially and in "soft law" relations. This is all the more necessary since the distinction between the Ex Ante and the Ex Post must be nuanced, in that its application is too rigid, in that it involves a long time (first of all the rules, then to apply them, then to notice a gap between rules and behaviors, then to repair it) is not appropriate if the system aims at the prevention of systemic crises, whose source is inside the operators. This is why the body in charge of solving the difficulties of the systemic banks for the salvation of the systeme meets the banking sector itself, to ensure that they are permanently "resolvable", so that the hypothesis of their resolution never arises. This is the challenge of this system: that it is always ready, for never be applying. - In the European Banking Union, the Single Resolution Board (SRB) is in charge of "resolve" the difficulties of European systemic banks in difficulty. It is the public body of the second pillar of the Banking Union. The first pillar is the prevention of these difficulties and the third is the guarantee of deposits. The resolution is therefore more like an Ex Post mechanism. But in this continuum through these three pillars between the Ex Ante and the Ex Post, the SRB does not wait passively – as would a traditional judge do – that the file of the troubled bank reaches it. Like a supervisor – which brings it closer to the first public in the system (Single Supervisory Board -SSB), which supervises all the banks, it is in direct contact with all the banks, and it approaches the hypothesis of a bank in trouble by a systemic perspective: it is therefore to the entire banking system that the SRB addresses itself. As such, it organizes meetings, where he is located: in Brussels. Thus, on June 18, 2019, all banks came to discuss with the Single Resolution Board to know what it wants from the banks and for the banks, in what is called a "dialogue meeting". To resolve in Ex Post the difficulties of a bank, it has to present a quality (a little known concept in Bankruptcy Law): "resolvability". How build it? Who build it ? In its very design and in its application, bank by bank. For the resolution body vis-à-vis all players in the banking and financial sector, it's clear: "Working together" is crucial in building resolvability ". In the projection that is made, it is affirmed that there can be a successful resolution only if the operator in difficulty is not deprived of access to what makes to stay it alive, that is to say the banking and financial system itself, and more specifically the "Financial Market Infrastructures", for example payment services. Does the Single Resolution Board expect spontaneous commitments from the FMIs for such a "right of access"? In this case, as the Single Resolution Board says, this right of access corresponds to "critical functions" for a bank, the resolution situation can not justify the closure of the service. By nature, these crucial operators are entities that report to regulators who oversee them. Who enforces – and immediately – this right of access? When one can think that it is everyone, it risks being nobody …. That is why the resolution body, relaying in this a concern of the Financial Stability Board, underlines that it is necessary to articulate the supervisors, regulators and "resolvers" between them. - To read this program, since it is a proposed program of work for the banking sector, four observations can be made: 1. We are moving more and more towards a general "intermaillage" (which will perhaps replace the absence of a global State, but it is an similar nature because it is always to public authorities that it refers and not to self-regulation); 2. But as there is no political authority to keep these guardians, the entities that articulate all these various public structures, with different functions, located in different countries, acting according to different temporalities, these are the companies themselves that internalize the concern that animates those who built the system: here the prevention of systemic risk. This is the definition of Compliance, which brings back to companies, here more clearly those those which manage the Market Infrastructures, the obligations of Compliance (here the management of systemic risk through the obligation of giving access). 3. Even without a  single systemic guard, there is always a recourse. That will be the judge. There are already many, there will probably be more in a system of this type, more and more complex, the articulation of disputes is sometimes called "dialogue". And it is undoubtedly "decisions of principle" that will set the principles common to all of these particular organisms. 4. We then see the emergence of Ex Ante mechanisms for the solidity of the systems, and the solidity of the players in the systems, and then the Ex Post resolution of the difficulties of the actors according to access to the solidity of the infrastructures of these systems, which ultimately depend on judges (throughout the West) facing areas where all of this depends much less on the judge: the rest of the world. -  

Articles

Bertrand Cantat revendique son “droit à la réinsertion” et le fait qu’il “a payé la dette à laquelle la justice l’a condamné” : en Droit, la justice pénale n’est pas une simple “facture” et c’est en terme de “libertés” et non de “droits” que les questions se posent